

EarnIn: Why Wait for Payday?
4.7

When a bill lands a few days before payday, I understand the appeal of getting access to wages sooner. But with any cash-advance app, convenience is only one part of the decision: I also want to know what the app asks me to connect, what choices I have, and whether an advance will actually help my budget rather than shift the same problem forward. That trust question matters more to me than a polished screen.
Start with the trade-off, not the cash-out button
EarnIn is a free finance app from Activehours Inc., and its central idea is to let eligible workers access some of their earned pay before payday. The app has a 4.7 average from around 286,000 ratings, with over 10 million installs. Those figures suggest it is widely used, but they are not a substitute for deciding whether its timing and repayment rhythm fit your own finances.
I would think of it as a short bridge, not extra income. If you use an advance to cover a necessary expense and can comfortably manage the smaller paycheck that follows, it may be useful. If you need cash every pay cycle just to make ordinary expenses work, repeated early access can make the next payday feel tighter. In that situation, I would first compare the cost and flexibility of other options, such as asking a bill provider about a due-date change or checking whether a lower-cost credit option is available.
Who is likely to find it useful
The best fit is someone with regular earnings who has a temporary timing mismatch: perhaps a prescription, a transit pass, or a necessary repair comes due before wages arrive. For example, if my paycheck is due later in the week but I need to pay for an urgent car repair to get to work, an advance could help bridge that gap. The sensible next step would be to check the amount I actually need, rather than treating the available limit as a target.
It is less suitable for someone whose income changes sharply from week to week, who has no room to absorb a smaller deposit on payday, or who is looking for a long-term way to handle debt. An advance can solve a timing problem, but it cannot make recurring expenses smaller. I would skip it if I could not clearly explain how the next paycheck would cover both the remaining bills and the money already accessed.
Use the limit as a ceiling, not a plan
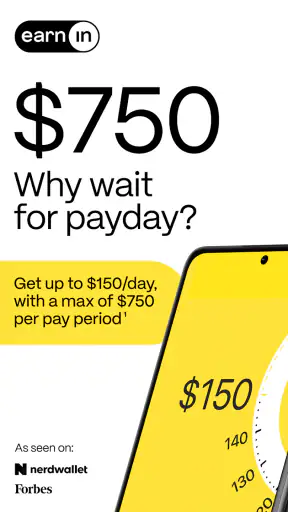
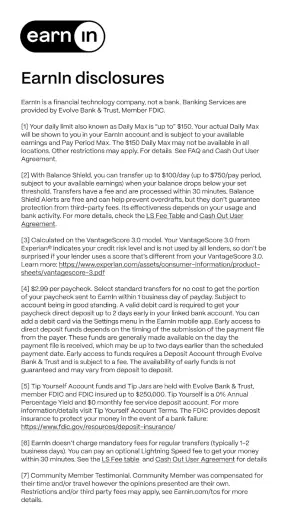
Before relying on any cash-out, I would check the current amount shown in the app and compare it with the expense in front of me. EarnIn’s stated access is up to $150 a day, with a maximum of $1,000 per pay period; those are ceilings, not a promise that every person can take out that amount. A smaller withdrawal may be the better choice because it leaves more of the next pay available for rent, food, and other scheduled payments.
A practical habit is to write down three things before confirming: the bill being covered, the cash needed to cover it, and the amount of the next paycheck that must remain available. That quick check helps distinguish a genuine emergency from spending that can wait. It also gives me a clear reason to stop rather than making another withdrawal simply because the app still shows room.
Check the path from setup to payday
The app’s setup involves linking a bank account and verifying employment details, so I would take a moment to read each prompt and make sure the accounts and work information are correct. These steps are central to an earned-pay service, but they also involve sensitive financial and employment information. I would only proceed on a device and network I trust, and I would avoid rushing through screens I do not understand.
Once set up, I would review the cash-out and repayment details before acting, then check my bank activity and the next pay deposit afterward. If the amount or timing does not match what I expected, I would pause before making another withdrawal and use the app’s support route to clarify it. A useful personal control is to keep a note of each advance and its purpose; that makes it easier to see whether the tool is solving occasional timing gaps or becoming part of the regular budget.
Using EarnIn with a clear view of the risks
I’d use this section to weigh the convenience of early access against the obligations waiting on payday, rather than judging the app by how quickly it can move money. A helpful final check is to compare the cash-out with bills already scheduled for the next deposit; that makes the trade-off concrete and sets up a more careful look at the choices you control.
Getting Started with EarnIn
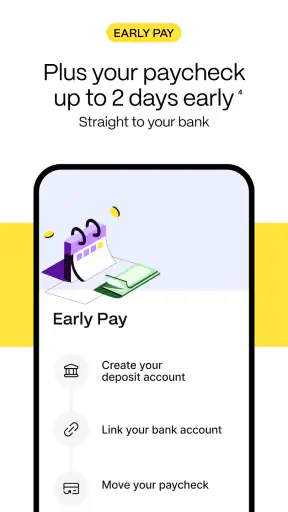
First things first, downloading the app is a breeze. Available on both Android and iOS, you can find it easily on the Google Play Store or the Apple App Store. Once you've got it installed, setting up your account is pretty straightforward. You’ll need to link your bank account and verify your employment details. I know, it sounds a bit daunting, but the app guides you through the process with clear instructions.
What really hooked me was how user-friendly the interface is. Everything is laid out in a way that even if you’re not tech-savvy, you’ll still find your way around without a hitch. It's like the app wants you to succeed!
How EarnIn Works
So, what’s the magic behind EarnIn? Essentially, it allows you to access the money you've already earned before your actual payday. Think of it as borrowing from yourself. You can cash out up to $100 per day, up to $500 per pay period. It’s perfect for those unexpected expenses that love to creep up when you least expect them.
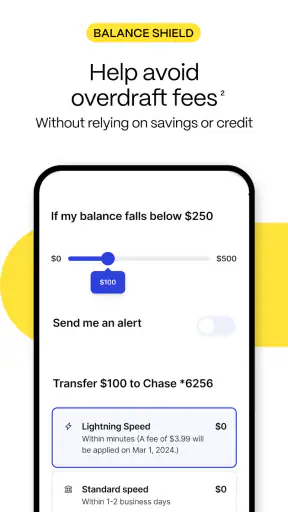
One of the coolest features is the "Balance Shield." This nifty tool alerts you when your bank balance is running low, and it can automatically cash out up to $100 to prevent overdraft fees. Honestly, it’s like having a financial guardian angel watching over your shoulder.
The Cost Factor
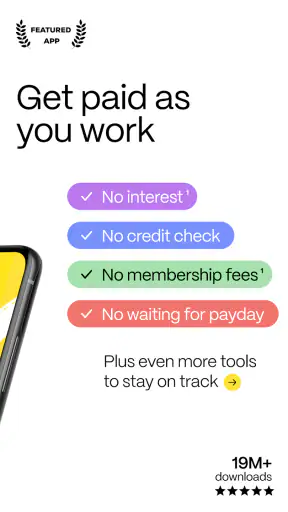
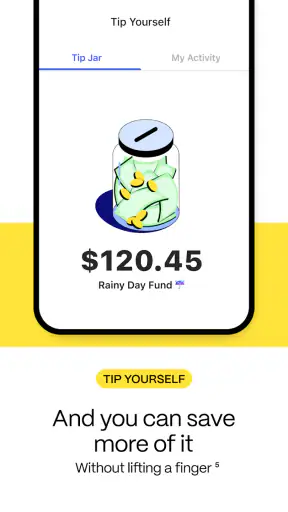
Now, you might be wondering about fees. Here’s the kicker: there aren’t any mandatory fees. Instead, EarnIn operates on a tip-based system. You decide how much you think the service is worth. It’s refreshing to see a company trust its users like that.
Of course, you can choose not to tip, but I found myself happy to throw a few bucks their way after realizing how much stress they’ve saved me from. Plus, it’s a great way to support a service that’s genuinely helpful.
Community and Support
Another aspect worth mentioning is the community vibe. EarnIn isn’t just about financial transactions; it’s about building a supportive network. Their "Health Aid" feature, for instance, allows users to crowdfund medical bills. It’s heartwarming to see people coming together to help each other out.
If you ever run into any issues, their customer support is top-notch. They’re responsive and genuinely seem to care about resolving any problems you might encounter. It’s a breath of fresh air compared to some of the other apps I’ve dealt with.
Privacy and Security
In today’s digital age, privacy and security are always a concern. The good news is, EarnIn takes this seriously. They use bank-level encryption to keep your data safe, so you can rest easy knowing your information is protected.
You can tell they’ve put a lot of thought into making sure users feel secure, which is a huge plus in my book.
Final Thoughts
All in all, if you’re looking for a way to ease the financial stress between paychecks, EarnIn is definitely worth checking out. It’s convenient, easy to use, and has a kind-hearted approach that makes it stand out from other financial apps.
Whether you’re dealing with unexpected expenses or just want a little extra cushion, this app is a solid addition to your financial toolkit. Give it a try and see how it can make your life just a little bit easier.
Make the decision around your pay pattern
The key question I would ask before installing is not simply “Can I get an advance?” but “Will I be able to leave enough in my next deposit for the bills that still need paying?” That makes the app most practical for a one-off mismatch between a known expense and a predictable payday. It is a weaker choice when hours, pay dates, or income vary enough that planning around the next deposit becomes guesswork.
EarnIn is free to download and is rated for Everyone. It was released on January 21, 2014, and its current version is 16.32, with Android 8.0 or later required. Those details help with basic compatibility, but I would still review the current in-app terms and prompts before connecting financial accounts. An app’s age or popularity alone does not tell me whether a particular cash-out suits my circumstances.
Small choices that can prevent a larger squeeze
One useful way to use an advance is to match it to a single, clearly defined expense rather than moving a general amount into your account. If the bill is smaller than the amount available, taking only what covers it reduces the chance that convenience turns into casual spending. I would also avoid making a second cash-out until I have checked the first one against the next payday’s expected obligations.
It helps to think through the whole sequence: money arrives early, the immediate bill is handled, and a later paycheck must still cover everything else. That final step is easy to overlook when the urgent expense is right in front of you. A simple calendar reminder to review the bank balance before payday can make the trade-off visible, especially if several automatic bills are due around the same time.
For someone comparing alternatives, the differences are mainly about timing and structure. A conventional personal loan is generally designed for a larger borrowing need with a repayment schedule, while a credit card can offer a revolving line but may carry interest if a balance remains. Asking a provider to move a due date may avoid borrowing altogether, though it depends on the bill and the provider. EarnIn is most compelling when the need is limited, near-term, and tied to earnings already received through work; it is not a replacement for a longer-term plan to reduce expenses or manage debt.
Keep trust decisions in your own hands
Because setup involves banking and employment details, I would treat every permission or account connection as a deliberate choice. Read the wording on each screen, check that the account is the one you intend to use, and consider whether you are comfortable with the information requested for the service to work. If anything feels unclear, waiting and reviewing it is better than agreeing just to reach the cash-out screen faster.
I would also separate two questions that are easy to blend together: whether the app is convenient, and whether I am comfortable with its data practices and account access. The first is about usability; the second deserves a careful look at the app’s current explanations and settings. I would not assume that a friendly interface settles the privacy question. The same caution applies to notifications or automatic options: I would review what is enabled and keep only what I genuinely want to use.
The tip-based approach described in the original app experience can feel more flexible than a mandatory charge, but a voluntary tip is still money leaving your account. I would decide based on my own budget rather than the emotional pressure of feeling grateful or guilty. If I choose to tip, I would include it in the total cost of that particular use; if I cannot afford it, I would not let the idea of tipping obscure the more important question of whether taking an advance is sensible.
A cautious verdict for the right kind of cash gap
My overall view is that EarnIn can be a useful short-term tool when a worker has a specific expense, a reasonably predictable payday, and enough discipline to account for the smaller deposit that follows. The interface and early-access model make the basic idea easy to understand, and the app’s scale gives a prospective user plenty of public feedback to consider. Neither point removes the need to check the current terms, available amount, and account choices for yourself.
I would not recommend relying on it as a routine way to make an unbalanced budget work. If every pay period begins with a new cash shortfall, I would look first at options that address the underlying timing or spending problem, and compare any borrowing carefully. For occasional gaps, though, the practical test is straightforward: know the reason, take no more than needed, understand what will happen at payday, and keep control of the decision. If those steps fit your situation, EarnIn may earn a place in your financial toolkit; if they do not, waiting for payday or choosing another route is the safer call.
4.7
138.93K Reviews
Pros
- Instant access to earned wages.
- User-friendly and intuitive interface.
- No hidden fees for transactions.
- Budgeting tools for better finance management.
- Seamless bank integration.
Cons
- Limited to certain banks.
- Requires consistent income source.
- Daily withdrawal limit applies.
- Not available in all states.
- May encourage overspending.


